LedgerSpring
Your Business Has Grown. Have Your Accounting and Financial Processes Kept Up?
LedgerSpring provides accounting, controllership, and finance-operations advisory services for growing service businesses.
We help you maintain reliable accounting and financial reporting, strengthen financial oversight, and identify opportunities to improve your financial processes.
CPA-led. 20+ years across accounting, financial management, internal controls, and business operations.
Services
Based in Illinois, serving clients nationwide.
Accounting
Accounting Services
Starting at $850/month
Reliable Accounting and Financial Reporting
Ongoing accounting services to keep your records accurate, manage the month-end close, and provide reliable financial reports so you can understand how your business is performing.
General ledger management
Account reconciliations
Month-end closing
Financial statement preparation
Accounting review and adjustments
Controllership
Controllership Services
Starting at $1,500/month
Experienced Financial Oversight for Growing Businesses
Already have a bookkeeper or accounting team? LedgerSpring provides experienced oversight, reviews financial reports, and strengthens accounting procedures and controls without a full-time controller.
Accounting oversight and supervision
Month-end close oversight
Financial reporting and analysis
Internal controls and procedures
Accounting workflow coordination
Finance Ops Reset
Finance Operations Reset
Starting at $1,950 (One-time assessment)
Find Out What's Holding Your Finance Operations Back
A structured assessment to identify weaknesses in your financial operations, investigate potential causes, and recommend practical improvements before you commit to significant changes.
Accounting processes and workflows
Financial and management reporting
Internal controls
Systems and technology
Roles and responsibilities
Different Financial Needs Require Different Solutions
As your business grows, your accounting and financial oversight needs change. The right support depends on what your business already has and where additional expertise is needed.
01 · ACCOUNTING
When Accounting Takes Time Away From Running Your Business
Your business needs accurate records and timely financial statements, but managing reconciliations, closing the books, and coordinating accounting work takes time away from running the business.
LedgerSpring provides ongoing accounting services to keep your financial records current and your monthly reporting on track.
02 · CONTROLLERSHIP
When Financial Oversight Becomes Essential
You already have a bookkeeper or accounting team handling the daily work. But who reviews the financial reports, oversees the monthly close, and ensures accounting issues receive appropriate attention?
LedgerSpring provides experienced controllership support to strengthen financial oversight and help management make better-informed decisions.
03 · FINANCE OPERATIONS RESET
When You're Not Sure What Needs to Change
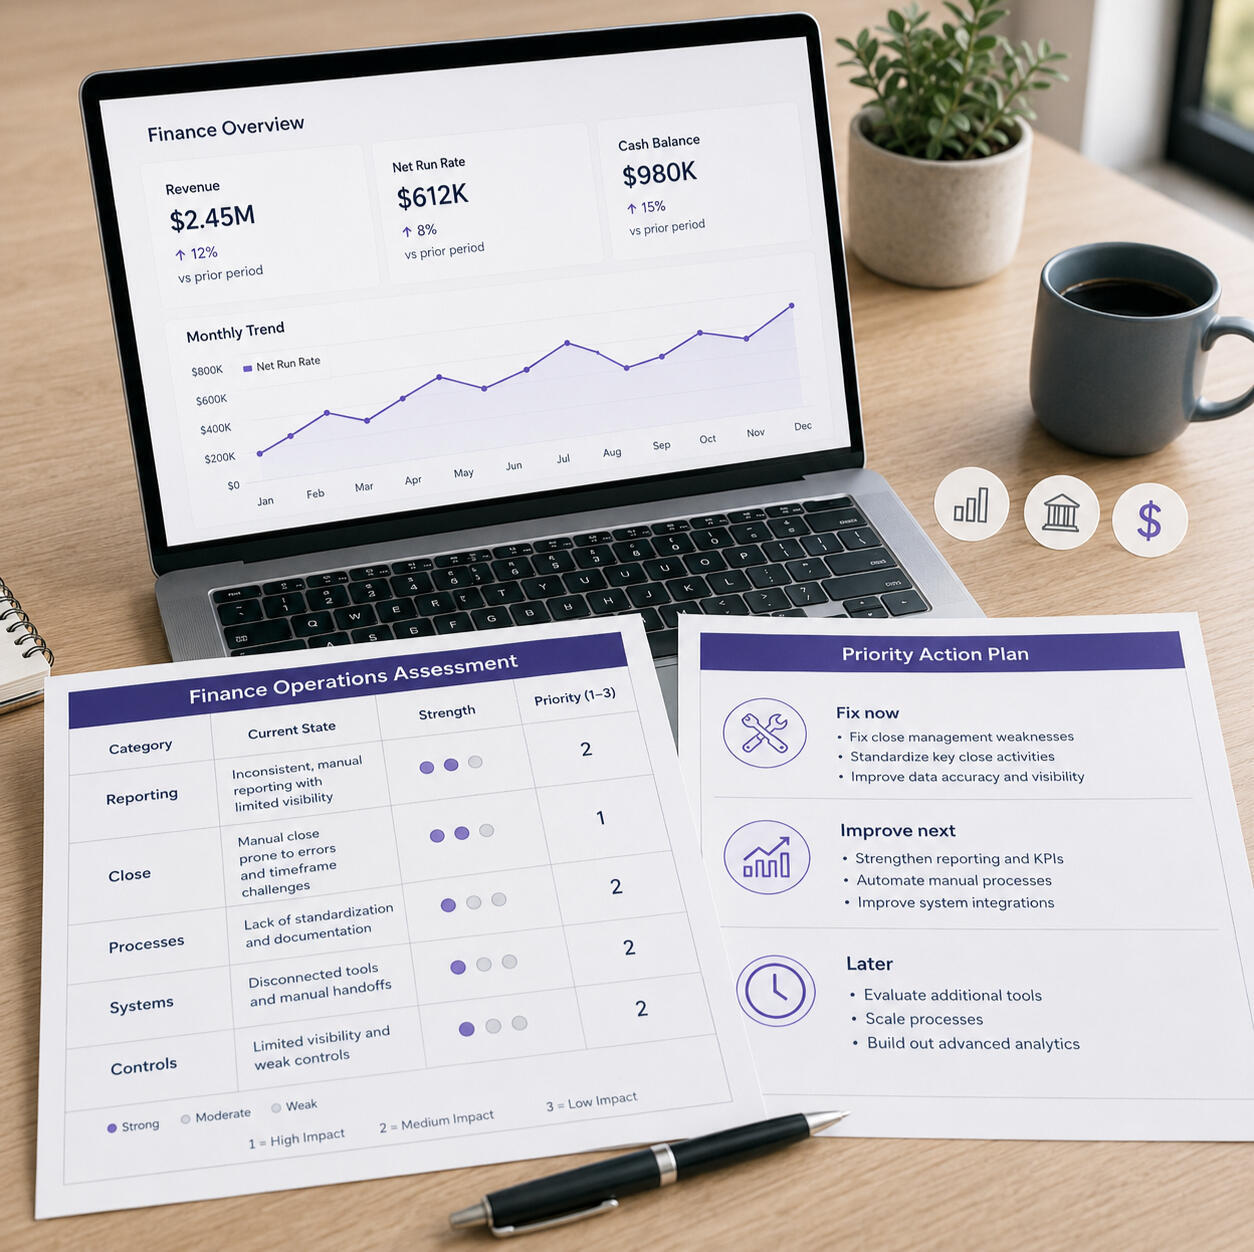
Financial reports are delayed, accounting work requires repeated corrections, or manual processes are consuming more time. You know something needs to improve, but the cause isn't clear.
The Finance Operations Reset investigates potential causes and recommends practical improvements before you commit to additional staff, new software, or major process changes.
Let's Discuss What Your Business Needs
Whether you're looking for reliable accounting, experienced financial oversight, or help improving your financial processes, we can discuss your situation and determine whether LedgerSpring's services are a good fit.
About LedgerSpring
Experienced Financial Judgment for Growing Businesses
Based in Illinois, serving clients nationwide.
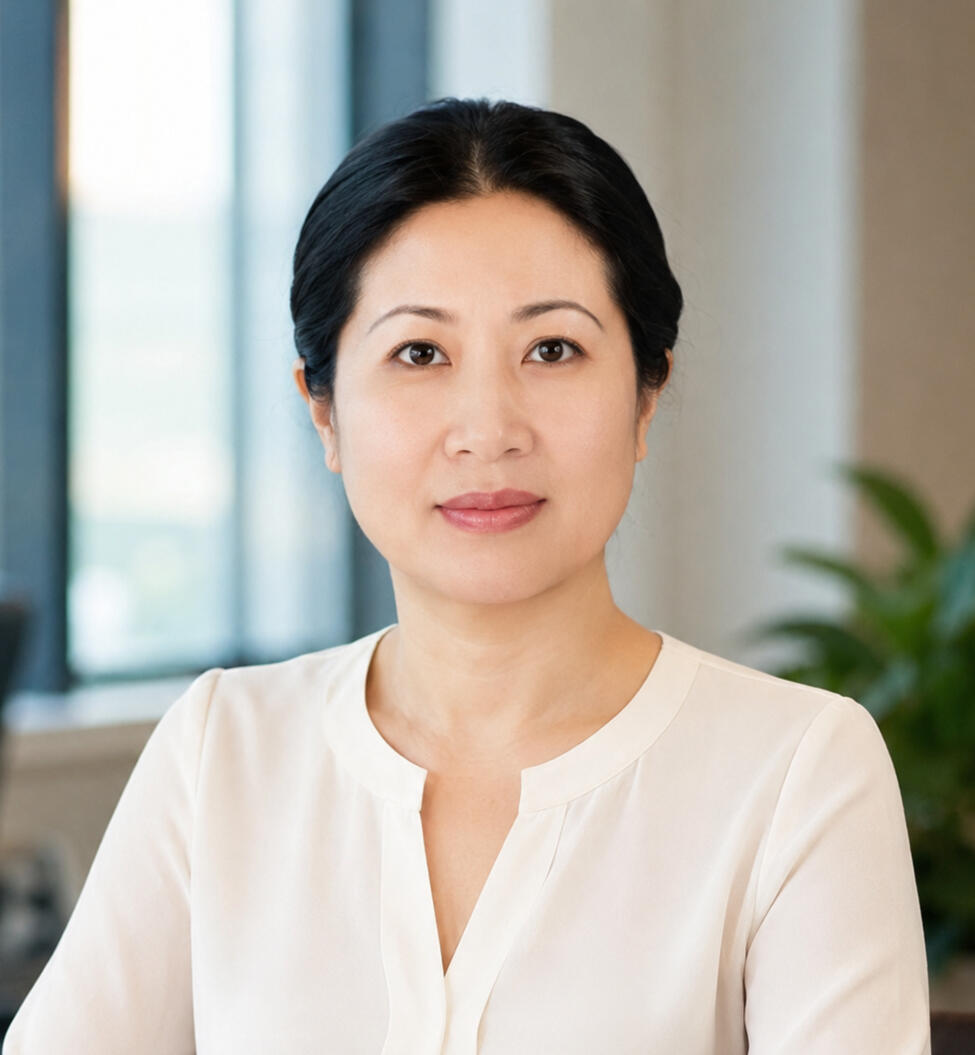
LedgerSpring is led by Mai Luu, CPA, CMA, CFE, with more than 20 years across accounting, financial management, internal controls, and business operations.That experience brings a broader perspective to client work. Beyond maintaining accurate financial records, LedgerSpring considers the accounting procedures, responsibilities, controls, and reporting practices that support reliable financial information and effective management oversight.
Why Finished Financial Reports Do Not Show How Well Your Accounting Process Works
Completed books do not guarantee strong finance operations. Reliable financial information also depends on the processes, responsibilities, controls, and systems behind them.Read the article →
How a Growing Business Outgrows Its Accounting and Financial Processes
As a business grows, finance processes can require more manual effort, follow-up, and rework. The challenge is knowing what work comes from growth and what comes from processes that have not kept up.Read the article →
Do You Need More People, Better Processes, or Better Systems?
When finance work keeps increasing, the answer is not always more staff. The real issue may be inefficient processes, unclear responsibilities, or systems that no longer fit the business.
Why Management Still Lacks Financial Visibility
If your team operates at full capacity but management still lacks timely, reliable information, the problem may lie in inefficient processes, unclear responsibilities, disconnected systems, or underused technology.
Contact Us
Send a message
Tell us a little about your business and the services you're interested in. We'll review your inquiry and follow up about next steps, including a 20-minute introductory conversation if appropriate.
CPA-LED ACCOUNTING & FINANCIAL OPERATIONS ADVISORY
Based in Illinois, Serving Clients Nationwide
©2026 LedgerSpring. All rights reserved.
Thank You
Your inquiry has been submitted successfully.
We'll review your message and follow up to discuss the next steps, including arranging a 20-minute introductory conversation if appropriate.
Why Finished Financial Reports Do Not Show How Well Your Accounting Process Works
.
Your company’s accounting work may get done every month, but the process could take far more employee time than you realize.Completed reconciliations and finished financial reports do not guarantee that every error was caught. Some transactions may still be missing, duplicated, or classified incorrectly.As the business grows, both the cost of completing the monthly close and the risk of undetected errors can increase.What Finished Reports Do Not ShowBy the time the financial statements reach the owner, all they see is the finished product.The numbers may be ready on time only because an experienced employee knows where the systems do not match and how to correct the recurring differences. Over time, that extra work becomes part of the routine.Because the expected report still gets produced, the owner may not see how inefficient the process has become or how much it depends on one person’s knowledge.One Process Weakness Can Create Two OutcomesFinancial reports are the final output of a longer process.Transactions may begin in the accounting system or in a billing, payroll, expense, or sales platform. The information has to be complete, classified correctly, moved between systems when necessary, and reviewed or reconciled.Consider a service business that needs a margin report by customer or service line. Employees must use the correct customer, project, or service codes when recording transactions. If they use those codes inconsistently, accounting has to investigate and reclassify the transactions before preparing the report.Accounting may identify and correct every classification problem. The final report would then be accurate, but producing it would require recurring investigation and delay the information management needs.Some incorrect classifications may remain. An unprofitable service could appear profitable, or one customer could appear more valuable than another. Management may then make pricing, hiring, or spending decisions using incorrect information.That same weakness can create extra work, bad information, or both.Manual work does not automatically produce inaccurate information. Reconciliations and reviews can identify many problems. But repeated data entry, unclear handoffs, inconsistent classifications, and undocumented adjustments create more opportunities for errors. A completed report does not prove that every error was found.Growth Increases the Cost and RiskA manual process or spreadsheet may work well when transaction volume is low and only a few people are involved. As the business grows, more people and systems handle the same information. Small inconsistencies begin creating more work.At lower volume, a recurring difference between two systems might take an hour to sort out. Once transaction volume grows, the same cleanup can consume most of a day. Before long, employees are turning to the owner regularly just to get the monthly work finished.The accounting team may work longer hours while less urgent but more strategically important work gets delayed, such as improving cash forecasts, analyzing margins, or correcting the process that keeps creating the extra work.At that point, management may conclude that the business needs another accounting employee. But more capacity does not fix the reason the extra work exists. It may simply allow the company to continue performing unnecessary work at a higher cost.Delayed information creates another cost. If accounting spends too much time assembling and correcting the numbers, management has less time to act on them.If the reports arrive weeks late, the owner may learn about a cash shortage only when payments are coming due. At that point, the company may have to delay payments or seek short-term financing instead of addressing the shortage earlier through stronger collections or spending decisions.Look at How the Information Is ProducedManagement should not evaluate the accounting operation only by whether they hit the monthly closing date.Start with the problems that return every month. What information arrives late or incomplete? Where do systems repeatedly fail to match? Which reports depend on spreadsheets or one employee’s knowledge? What important work gets delayed because the team spends its time correcting the same issues?That helps management see which work is actually necessary and which work exists because the process is weak.The answer may be as simple as clarifying who owns a task, changing how transactions are recorded, improving a handoff between departments, or making better use of an existing system. Before hiring another person or buying another system, management should first understand why the work keeps piling up.Reliable financial records remain essential. But completed financial reports do not prove that the accounting operation works efficiently or that every number is correct.
Management needs to look at both the financial information and the process that produces it.
ABOUT THE AUTHORMai Luu, CPA, CMA, CFE, has more than 20 years of experience across accounting, finance, internal controls, and business operations. Her work has included financial reporting, controllership, process improvement, internal controls, and the financial infrastructure businesses rely on as they grow.
©2026 LedgerSpring. All rights reserved.
How a Growing Business Outgrows Its Accounting and Financial Processes
.
As a business grows, the amount of work required to keep finance running often increases. Some of that increase is unavoidable. More transactions, employees, customers, locations, or services create additional financial activity and can introduce new complexity.The harder question is whether all of the additional effort comes from growth itself. A process that once worked efficiently may still produce the expected result while requiring more follow-up, corrections, reconciliations, management intervention, and reliance on individual knowledge to keep it moving.Because the work still gets completed, management can easily treat that added effort as a normal cost of running a larger company.Some of it is. But some can come from finance processes that have not changed as the business around them has changed.That distinction matters because a process does not have to fail before it begins creating unnecessary cost and friction.A working process can still be outgrownFinance processes develop around the circumstances of the business at the time.At low transaction volume, manually entering information may be faster and less expensive than implementing an integration. When an owner is closely involved in daily operations, asking the owner to approve certain purchases may be an efficient control. When only two people participate in a process, an informal handoff may work because each person understands what the other needs.Those arrangements may be entirely appropriate.The issue arises when the circumstances change while the process remains substantially the same.Many more transactions may now pass through the same manual process. More employees may originate purchases, submit expenses, approve work, manage projects, or provide information to accounting. The owner may no longer be close enough to daily activity to resolve every question quickly. Management may need financial information at a different level of detail or sooner than it did when the company was smaller.Research on finance functions in small and midsize businesses reflects this broader change. As businesses develop, finance often expands beyond transaction processing to support more formal processes, monitoring, planning, controls, and management decision-making. The way that evolution occurs varies considerably by company.A process can lag behind those changes without breaking. People compensate by spending more time moving information, following up, reconciling differences, resolving exceptions, and explaining what happened.The result may still be correct. What has changed is what the business has to do to produce that result.Not all additional finance work means the same thingA larger business legitimately creates more finance work.A company issuing more invoices has more billing activity. More employees create additional payroll and expense transactions. Additional projects, services, entities, or locations can create real accounting and reporting complexity. Some growing businesses simply need more finance capacity.That workload should be distinguished from work created by the process itself.Consider a company whose billing volume has increased substantially. Processing more customer invoices is a consequence of growth. Having an employee enter customer and project information into one system and then re-enter much of the same information into the accounting system is different. The first activity exists because the business has more activity to process. The second exists because of how information moves through the process.The same distinction applies when accounting repeatedly follows up with managers for information that is incomplete or inconsistent. More managers and transactions naturally produce more activity. Repeatedly correcting the same missing information or classifications adds work because the process does not reliably produce what accounting needs.The boundary is not always precise. Finance processes contain review, judgment, control, and exception handling that cannot simply be divided into necessary and unnecessary work. A more complex business may also require additional controls or analysis that appropriately increase finance effort.The distinction gives management a more useful way to interpret increasing finance workload. A busier finance team does not by itself tell management how much of the additional work is required by the larger business and how much is being created by the process.Growth changes the conditions around the processSeveral changes can alter what a finance process requires without making the process visibly fail.Volume is the most straightforward. A manual task that takes a few minutes may deserve little attention when it occurs occasionally. If the same task is repeated hundreds of times, the cumulative effort changes. Increased frequency can also change the economics of automation when the work is repetitive, predictable, and rules-based. That does not mean every high-volume activity should be automated. Implementation cost, exceptions, controls, and process stability still matter.Growth can also put more people into the same process. An informal handoff that works between an owner and a bookkeeper may become harder to manage when information passes among sales, operations, project managers, accounting, and management. The process now has to coordinate more participants. If responsibilities, required information, and handoffs remain informal, more activity can bring more follow-up, inconsistent treatment, and correction.Delegation introduces a different pressure. In a smaller business, an owner or experienced employee may supply much of the judgment and context that keeps financial work moving. That person knows which exceptions are reasonable, where missing information can be found, who needs to answer an unusual question, or why two numbers do not agree. At limited scale, relying on that knowledge can be efficient.As responsibilities are delegated, however, other people need to perform work that previously depended on immediate access to the owner or another experienced employee. A process that appeared simple may turn out to have depended on interpretation and intervention that were never incorporated into the process itself.Management's information needs can change too. A process may continue recording transactions accurately while management begins asking finance to provide information sooner, at greater detail, or in a form that supports decisions across a more complex business. The process is now being asked to do more than it was originally designed to support.These changes do not occur in every growing company or at the same pace. Revenue can increase without a comparable increase in transaction volume, employees, or operating complexity. Some simple manual processes remain efficient for years. The relevant issue is whether the conditions that made a process practical still exist.The cost appears before the failureWhen a process no longer fits those conditions, the business often keeps it functioning by supplying additional effort around it.Accounting performs another reconciliation. An employee maintains a manual bridge between systems. Managers answer recurring questions or correct information after it reaches finance. The owner continues making routine decisions because approval responsibilities have not changed. An experienced employee remembers how exceptions are handled.Each accommodation may be reasonable in isolation. The cost becomes more significant when the same accommodations recur across more transactions and more people.Some of that cost appears directly in employee time. Time spent repeatedly moving, correcting, reconciling, or locating information is time that cannot be spent on other finance responsibilities. Research on financial reporting processes has similarly identified rework, reconciliation, manual reporting tasks, and unresolved process issues as contributors to reporting effort and delay.The cost can also appear as slower financial information. If more data has to be assembled manually, more discrepancies have to be reconciled, or more questions must be resolved before accounting can complete its work, management waits longer for usable information. The accounting may still be correct, but the path to getting there has become longer.Bottlenecks develop when increasing activity continues to pass through the same decision point. Owner involvement that was efficient when there were relatively few decisions may become a constraint when substantially more transactions require the owner's attention. The problem is not owner involvement itself. The volume and responsibilities surrounding that involvement have changed.Delegation becomes harder for a similar reason. Giving responsibility to another employee does not accomplish much if that person must repeatedly return to the owner or a long-tenured employee for context that exists nowhere else in the process. Over time, the business can become more dependent on particular people precisely because those people know how to keep imperfect handoffs and workarounds functioning.These costs can remain difficult to see because capable people keep the work moving. Management sees completed work rather than the accumulated effort behind it.A growing company may legitimately need additional finance staff, and increased staffing is not evidence that its processes are weak. But before assuming that every increase in workload is simply a capacity issue, management should understand what is consuming the capacity. Additional people may be needed to support genuinely greater business activity. Repeated rework, manual data movement, unnecessary follow-up, and recurring intervention deserve a different question.Technology can remove some of that burden, particularly where work is repetitive and rules-based, but technology is not the definition of a scalable process. Sometimes the appropriate change is clearer responsibility, a simpler workflow, better use of an existing system, or elimination of a step that no longer serves a useful purpose.The objective is not to eliminate every manual task or make finance more sophisticated for its own sake. It is to avoid treating unnecessary friction as an unavoidable cost of running a larger business.Judge the process by what it now takes to keep it workingA finance process should not be evaluated only by whether the task eventually gets completed.Management also needs to understand what has accumulated around the process to make that completion possible. The relevant issue is not whether some manual work, management involvement, or individual judgment remains. Those may continue to be appropriate.The better question is whether the effort surrounding the process still makes sense for the business it now supports.How much of the work required to keep this process functioning is necessary because the business has grown, and how much exists because the process has not changed with it?Sometimes the answer will be that the existing process remains the simplest and most economical choice. In other cases, recurring manual effort, rework, intervention, or delay will show that a process designed for an earlier stage of the business is now adding materially to the cost and difficulty of operating the current one.A process that once worked well was not necessarily badly designed, but as the business changes, management needs to reconsider whether the assumptions that made that process work still hold.
ABOUT THE AUTHORMai Luu, CPA, CMA, CFE, has more than 20 years of experience across accounting, finance, internal controls, and business operations. Her work has included financial reporting, controllership, process improvement, internal controls, and the financial infrastructure businesses rely on as they grow.
©2026 LedgerSpring. All rights reserved.
Article 3
.
abc
ABOUT THE AUTHORMai Luu, CPA, CMA, CFE, has more than 20 years of experience across accounting, finance, internal controls, and business operations. Her work has included financial reporting, controllership, process improvement, internal controls, and the financial infrastructure businesses rely on as they grow.
Article 4
.
abc
ABOUT THE AUTHORMai Luu, CPA, CMA, CFE, has more than 20 years of experience across accounting, finance, internal controls, and business operations. Her work has included financial reporting, controllership, process improvement, internal controls, and the financial infrastructure businesses rely on as they grow.
Accounting & Controllership Services for Growing Businesses
LedgerSpring provides ongoing accounting and controllership services tailored to your business's needs, whether you need help managing your accounting or experienced oversight of an existing team.
Services starting at $850/month
Choose the Right Level of Accounting Support
Reliable accounting and timely financial reporting help you understand how your business is performing. Experienced financial oversight helps ensure accounting issues receive appropriate attention.
Accounting Services
Starting at $850/month
Reliable Accounting and Financial Reporting
For businesses that need ongoing accounting support to maintain accurate records, manage monthly closing, and prepare reliable financial statements.
Services may include:
General ledger management
Account reconciliations
Month-end closing
Financial statement preparation
Accounting review and adjustments
Controllership Services
Starting at $1,500/month
Experienced Financial Oversight for Growing Businesses
For businesses with existing accounting activities that need stronger oversight, review, financial analysis, and accounting procedures.
Services may include:
Accounting oversight and supervision
Month-end close oversight
Financial reporting and analysis
Internal controls and procedures
Accounting workflow coordination
Accounting and Controllership Services are available separately or together. Controllership does not automatically include routine accounting work. Preferential pricing is available for combined engagements, based on the agreed scope.
LedgerSpring is led by Mai Luu, CPA, CMA, CFE. Her experience across accounting, financial management, internal controls, and business operations brings a practical perspective to financial reporting, accounting oversight, and the processes that support them.
The Right Support Depends on What Your Business Needs
LedgerSpring offers Accounting and Controllership Services separately or together, depending on your existing accounting resources and reporting needs.
When You Need Dependable Accounting
Your business needs accurate records and timely financial statements, but managing the accounting work yourself takes time away from running the business.
LedgerSpring handles ongoing accounting activities, month-end closing, and financial statement preparation so you have reliable financial information without managing every detail yourself.
When Financial Oversight Becomes Essential
Your bookkeeper or accounting team handles daily transactions and prepares financial reports. But who reviews the reconciliations, oversees the month-end close, and addresses accounting issues that require additional expertise?
LedgerSpring provides experienced controllership support to strengthen accounting oversight and financial reporting without requiring a full-time controller.
When You Need Both
Your business needs ongoing accounting support, but you also want experienced oversight of the work, financial reporting, and internal controls.
LedgerSpring can manage the agreed accounting activities while providing controller-level review and supervision.
Businesses engaging us for both services benefit from preferential pricing based on the combined scope.
What You Can Expect
Reliable Financial Information. Stronger Oversight. Clearer Accountability.
Our services are designed to help growing businesses maintain dependable accounting and financial reporting.
Consistent Accounting Processes: Accounting activities, reconciliations, and month-end closing performed consistently, reducing the need for management to follow up on routine accounting work.
Reliable Financial Reporting: Timely financial statements that help management understand business performance and identify matters requiring attention.
Experienced Accounting Oversight: For controllership engagements, experienced review and supervision to identify accounting issues, strengthen reporting reliability, and provide additional financial oversight.
Better Coordination and Accountability: Defined responsibilities, established accounting procedures, and regular communication to help keep accounting work coordinated and issues appropriately addressed.
Specific responsibilities, reporting deliverables, and service levels are established in each engagement.
How We Work
01 — Understand Your Business
We begin with a conversation about your accounting needs, existing processes, reporting requirements, and current challenges.
02 — Define the Services
We review the relevant information and propose a scope of work outlining services, responsibilities, deliverables, and fees.
03 — Establish the Working Process
Once engaged, we coordinate access to accounting records and systems, confirm working procedures, and establish a recurring reporting and communication schedule.
04 — Provide Ongoing Support
LedgerSpring performs the agreed accounting or controllership services, addresses matters within scope, and communicates issues requiring management's attention.
Who We Work Best With
LedgerSpring serves growing service businesses that need dependable accounting, experienced financial oversight, or both.
A good fit typically includes businesses that:
Need ongoing accounting or controllership support rather than a one-time project.
Use QuickBooks Online or another mutually agreed-upon accounting system
Can provide access to relevant financial records and supporting information
Have management available to discuss financial matters and make necessary decisions
Value consistent accounting procedures, reliable reporting, and clear responsibilities
When Another Service May Be More Appropriate
LedgerSpring may not be the right fit if your primary need is tax preparation, financial statement audits or reviews, or extensive historical reconstruction of accounting records.
If your business is experiencing recurring accounting or financial-process problems and the causes aren't clear, a Finance Operations Reset may help identify weaknesses and determine which improvements to prioritize.
Let's Discuss Your Accounting and Financial Oversight Needs
Whether you need ongoing accounting, experienced controllership support, or both, let's discuss your business and what you're looking for.
We'll explore your requirements and determine whether LedgerSpring's services are a good fit.
CPA-LED ACCOUNTING & FINANCIAL OPERATIONS ADVISORY
Based in Illinois, Serving Clients Nationwide
©2026 LedgerSpring. All rights reserved.
Find Out What's Holding Your Finance Operations Back
Recurring accounting problems, delayed reporting, or inefficient processes can be difficult to resolve when the causes aren't clear.The Finance Operations Reset examines your financial operations, investigates potential causes, and provides practical recommendations to help you decide what to improve and where to start.
Assessments starting at $1,950.
Choose the Right Level of Assessment
Each Finance Operations Reset follows LedgerSpring's seven-area assessment framework. The depth of investigation and recommendations vary based on your business's complexity and needs.
Focused assessment
Reset Essentials
$1,950
For businesses with straightforward operations and clearly defined concerns.
What's included
Review across seven assessment areas
Targeted financial record and process review
Focused management discussion
Evaluation of key weaknesses and potential causes
Written findings and recommendations
Prioritized next steps
Final review meeting
FEATURED Core Assessment
Reset Comprehensive
$2,950
For businesses with recurring or interconnected financial-operations problems.
Includes Essentials, plus
Additional financial records and supporting evidence reviewed
Discussions with relevant accounting personnel
Walkthroughs of selected accounting workflows
Investigation of relationships between significant issues
Evidence-supported analysis of potential causes
Detailed improvement recommendations
90-day prioritized improvement roadmap
Expanded assessment
Reset Advanced
Custom pricing based on complexity
For complex operations requiring broader or specialized investigation.
Customized scope may include
Expanded management and employee interviews
Cross-functional workflow and control analysis
Detailed review of significant system dependencies
Evaluation of improvement alternatives and tradeoffs
Expanded recommendations and implementation roadmap
Additional management review discussions
The appropriate package, scope, timeline, and deliverables are confirmed before engagement. The Finance Operations Reset provides assessment and recommendations. Implementation is not included.
CPA-Led. Over 20 Years of Accounting and Financial Management Experience
LedgerSpring is led by Mai Luu, CPA, CMA, CFE. Her experience across accounting, financial management, internal controls, and business operations brings a practical perspective to evaluating financial processes and identifying opportunities for improvement.
Signs Your Business May Need a Finance Operations Reset
Your accounting and financial processes may still be built for the business you used to have, not the business you are running today.
Recurring accounting problems: Corrections, reconciliation issues, or reporting errors keep returning.
Delayed financial reporting: Month-end closing takes too long, leaving management waiting for information.
Increasing manual work: Spreadsheets, duplicate entry, follow-up, and rework consume more time.
Limited financial visibility: Management receives reports but still struggles to obtain timely, useful information.
Unclear responsibilities: Important activities depend on particular employees, with inconsistent oversight or approvals.
Uncertainty about solutions: You're considering more staff, new software, or automation but aren't sure what will solve the problem.
Understand the Cause Before Choosing the Solution
Hiring another employee, replacing software, or introducing automation may help. But without understanding the underlying causes, these changes may not resolve the problem.
The Finance Operations Reset investigates significant weaknesses, evaluates potential causes, and helps management prioritize improvements.
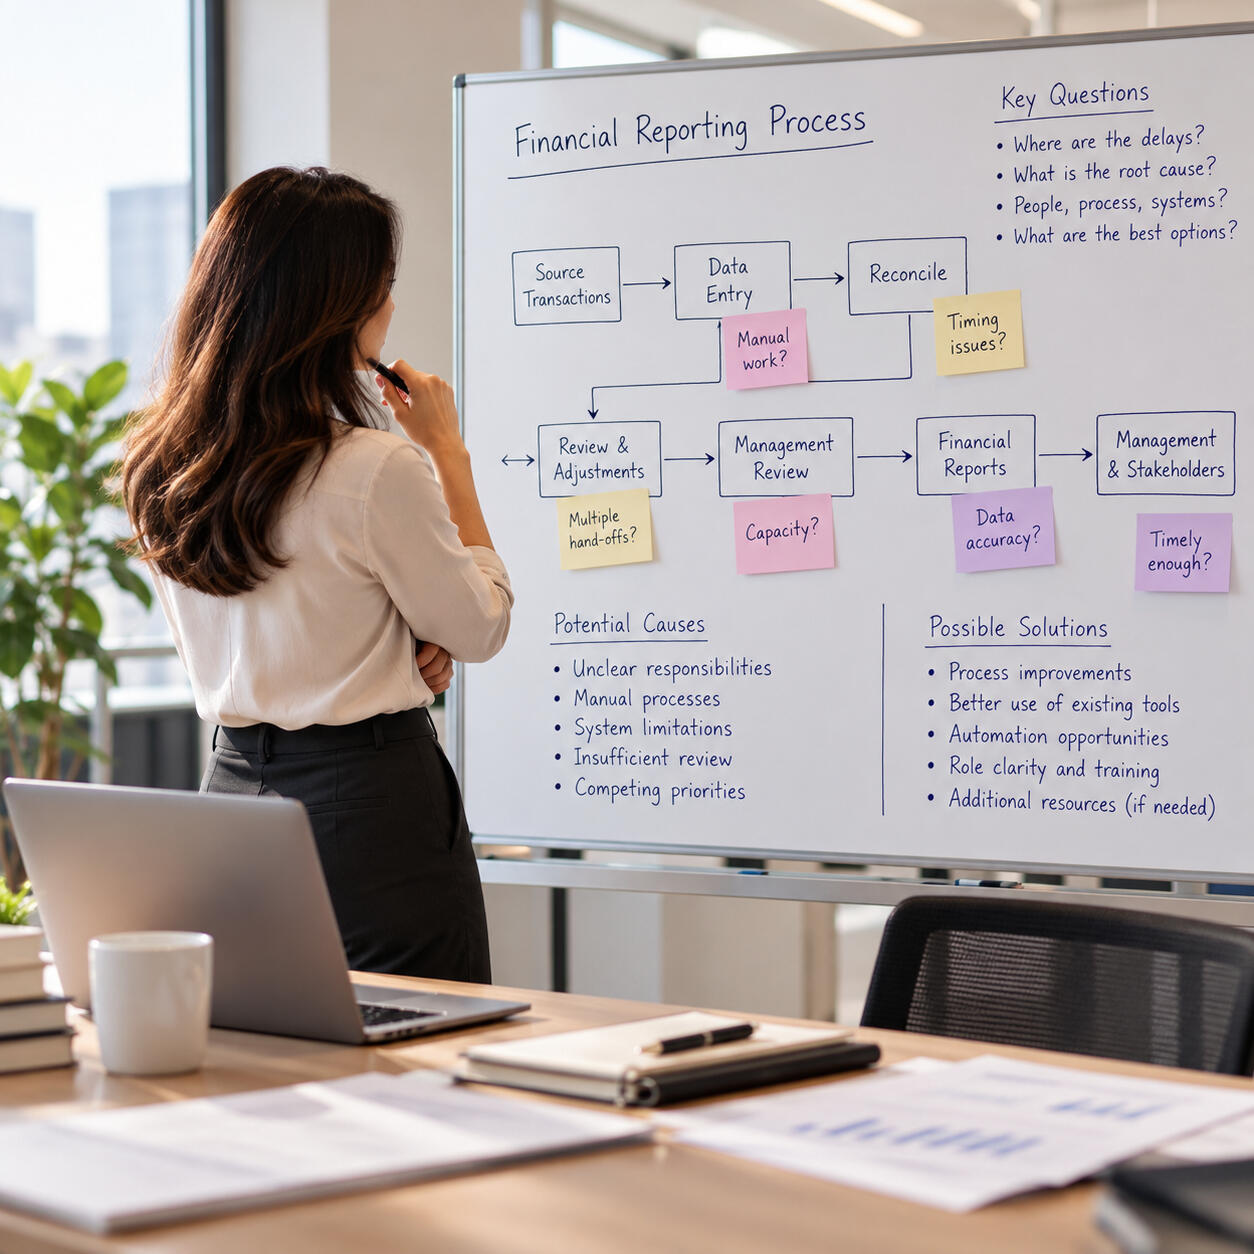
What We Review
The Finance Operations Reset examines seven interconnected areas to understand how your accounting and financial operations function and where improvements may be needed.
Financial Reporting: Accuracy, timeliness, consistency, and usefulness of financial information provided to management.
Cash Visibility and Cash Flow Management: How cash balances, upcoming cash requirements, and cash-flow information are monitored and managed.
Month-End Close: Closing procedures, reconciliations, recurring corrections, bottlenecks, and reporting delays.
Accounting and Financial Workflows: Manual activities, duplicate work, information handoffs, follow-up, and process inefficiencies.
Systems and Technology: How financial systems work together, where limitations exist, and how technology affects accounting workflows.
Internal Controls and Accountability: Approvals, oversight, segregation of duties, responsibilities, and dependence on key employees.
Readiness for Growth: Whether existing processes, systems, and responsibilities can support increasing business complexity.
The depth of investigation depends on the selected Reset package and agreed scope.
What You Receive
Clear Findings. Practical Recommendations. Prioritized Next Steps.
The Finance Operations Reset provides documented findings on your financial operations, with practical recommendations and prioritized next steps based on the assessment.
FINANCE OPERATIONS FINDINGS: Documented observations, identified weaknesses, and associated risks across the areas reviewed.
IMPROVEMENT RECOMMENDATIONS: Practical actions to address weaknesses in accounting processes, reporting, controls, responsibilities, and systems.
PRIORITIZED NEXT STEPS: Recommended improvements organized by importance and dependencies. Comprehensive includes a more detailed 90-day prioritized improvement roadmap.
FINAL REVIEW MEETING: A discussion of the findings, recommendations, and priorities, with an opportunity to clarify next steps.
The depth of analysis and detail of the deliverables depend on the selected Reset package and agreed scope.
How It Works
From Initial Conversation to Practical Recommendations
01
Confirm the Fit
Understand your needs and agree on the scope.
02
Gather Information
Obtain relevant records and process information.
03
Conduct the Assessment
Evaluate evidence and develop findings and recommendations.
04
Review Next Steps
Receive your findings and discuss recommended priorities.
Assessment timelines are confirmed before engagement and depend on scope and information availability.
Is the Finance Operations Reset Right for Your Business?
Designed for growing service businesses with established accounting operations that need an independent assessment of their financial processes.
Who We Work Best With
A good fit typically includes businesses that:
Have existing accounting records and financial reporting processes.
Use QuickBooks Online or another agreed-upon accounting system.
Can provide relevant financial records and process information.
Have management and accounting personnel available to participate in the review.
Are willing to review findings and consider practical improvements.
When Another Service May Be More Appropriate
The Reset may not be the right starting point if your business primarily needs:
Ongoing bookkeeping, accounting, or controllership services.
Historical accounting cleanup or reconstruction of financial records.
Tax preparation, tax planning, or financial statement assurance services.
Software implementation rather than an independent assessment.
If your business already knows it needs ongoing accounting or controllership support, LedgerSpring offers these services directly without requiring a Finance Operations Reset.Explore Accounting & Controllership Services →
Let's Discuss Your Finance Operations
Not sure whether your business needs a Finance Operations Reset?
Tell us about your current challenges. We'll discuss whether an assessment is appropriate and, if so, which level best fits your needs.
CPA-LED ACCOUNTING & FINANCIAL OPERATIONS ADVISORY
Based in Illinois, Serving Clients Nationwide
©2026 LedgerSpring. All rights reserved.